A 3:1 LTV:CAC ratio doesn’t mean you can afford more growth. Before I increase acquisition spending, I check whether customers stay, generate gross profit, and repay acquisition costs within the time my cash runway allows.
I use five frameworks to answer different questions:
- Cohorts: Are newer customers performing better than older ones at the same customer age?
- Channels: Where should the next acquisition dollar go?
- Profit margins: How much customer revenue remains after serving costs?
- CAC payback: How long does it take to recover acquisition spending?
- Scenarios: Does the plan still work if churn or CAC increases, or margins fall?
Quick Comparison
| Framework | What I compare | Decision it supports |
|---|---|---|
| Cohorts | Customer groups at the same age | Increase, hold, or cut spending |
| Channels | CAC, retention, volume, and returns by source | Move budget between channels |
| Profit margins | LTV after serving costs | Change pricing or reduce costs |
| CAC payback | Recovery time versus cash runway | Set the pace of growth |
| Scenarios | Base, downside, and upside results | Set spending limits and review triggers |
My rule: use consistent costs and time periods, keep observed results separate from forecasts, and <u>check a second framework before scaling</u>.
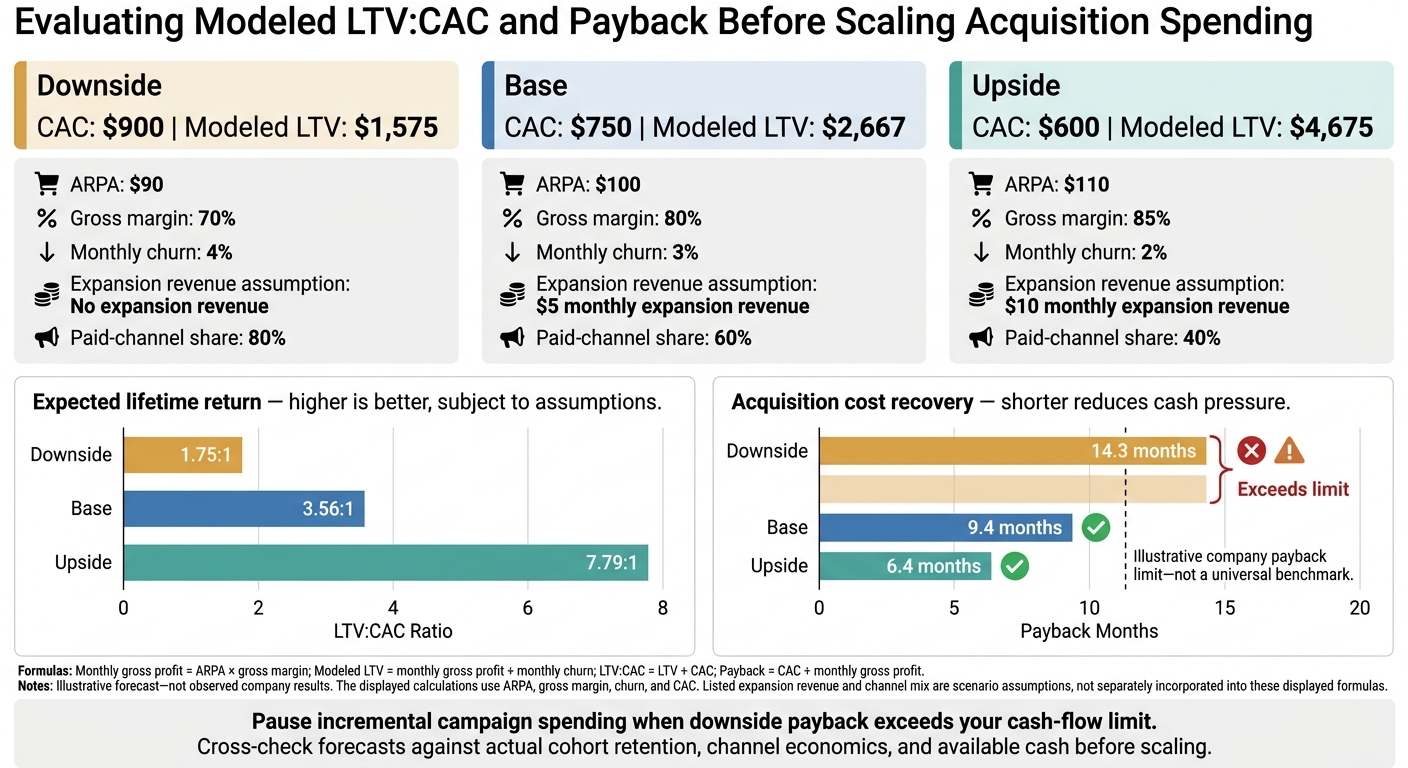
LTV:CAC Scenario Comparison: Returns vs. Payback
How to Calculate CAC & LTV | The 2 Key Metrics for Growth
sbb-itb-17e8ec9
Define CAC, LTV, and LTV:CAC
CAC = total sales and marketing spend tied to acquisition ÷ new paying customers. Count salaries, commissions, bonuses, agencies, events, content, software, and attributable overhead. Leave out product costs, general admin, and unrelated customer success costs.
Match acquisition spend to the customers it helped win. For long sales cycles, use a lagged or rolling window that reflects how long the sales process takes.
LTV estimates gross profit per customer over the relationship - not total revenue. For subscriptions, use LTV = average monthly revenue per customer × gross margin ÷ monthly customer churn.
An LTV:CAC ratio of 3:1 means $3 in expected gross profit for every $1 spent on CAC. These inputs give you a consistent basis for comparing cohorts, channels, margins, payback, and scenarios.
Treat 3:1 as a benchmark, not a target. The right ratio depends on margins, retention, company stage, cash, sales-cycle length, and whether the inputs are observed or forecast. Keep the customer unit, currency, and time basis consistent, and label observed ratios separately from forecasts. The first framework uses this baseline to compare LTV:CAC by customer cohort.
1. Compare LTV:CAC by Customer Cohort
Business Question and Decision
Use the CAC and LTV definitions above to check whether newer customers outperform older ones. Group customers by their first paid month or quarter, then decide whether to increase, hold, reduce, or redirect acquisition spend. Monthly cohorts suit higher-volume businesses. Quarterly cohorts usually give more stable results for lower-volume or enterprise businesses.
Required Financial Inputs
For each cohort, collect its size, attributable acquisition spend, revenue by customer and month, direct serving costs, and active-customer counts. Account for refunds, discounts, expansion, and contraction. Keep cost categories consistent across cohorts.
Calculation Method
Build a matrix with acquisition cohorts as rows and customer age as columns. Calculate cohort CAC = attributable acquisition spending ÷ original customers. Track retention alongside the matrix to help explain each cohort’s curve.
Observed LTV:CAC at age t = cumulative cohort gross profit through t per original customer ÷ cohort CAC.
Compare cohorts at the same age - for example, month 3, 6, or 12. Always use the original customer count, not the number of surviving customers.
Limitations and Assumptions
Observed results show performance so far, not lifetime results. Keep observed results, projected gross profit, and modeled lifetime LTV:CAC separate.
Small cohorts, seasonality, promotions, and product changes can skew comparisons. Use the same reporting cutoff and cost-allocation method for every cohort, then update forecasts as cohorts mature. Use the analysis to guide spending decisions, not just report past performance.
This cohort view tracks whether the ratio improves over time. The next framework checks whether that improvement comes from specific channels.
2. Compare LTV:CAC by Acquisition Channel
Business Question and Decision
After cohort analysis, compare LTV:CAC by channel to see which acquisition source delivers the strongest economics. Which channel deserves the next dollar? Weigh the ratio against customer volume, sales-cycle length, and room to scale. A high ratio offers little if the channel brings in few customers or is hard to grow. A lower ratio may be the better choice if it pays back faster or supports business growth goals. If margins differ by channel, use the next framework to adjust for profit.
Required Financial Inputs
For each channel, collect attributed new customers, average monthly revenue per customer or account, gross margin, retention or churn, and sales-cycle length. Use fully loaded CAC - not just ad spend. Include media, creative production, agency fees, commissions, software, sales and marketing payroll, and overhead. Match spending to conversion timing so long sales cycles don't skew the comparison.
Calculation Method
Assign direct expenses to the channel that incurred them. Allocate shared costs using a driver such as employee hours or campaign spend, then calculate CAC and LTV the same way across channels.
Channel CAC = (direct costs + allocated shared costs) ÷ attributed new customers
Margin-adjusted LTV = (average monthly revenue per customer × gross margin) ÷ monthly churn rate
LTV:CAC = margin-adjusted LTV ÷ fully loaded channel CAC
Hypothetical comparison - not company results. Customer volumes cover the same reporting period; LTV figures are modeled gross profit.
Channel CAC LTV LTV:CAC Customer volume Sales cycle Key limitation Paid search $1,800 $7,200 4.0x 120 21 days Competitive keywords may raise costs Content and SEO $900 $5,400 6.0x 45 60 days Requires months of content investment Outbound sales $3,500 $14,000 4.0x 35 75 days High labor and management costs Referral partners $1,200 $4,800 4.0x 20 30 days Partner capacity may be limited
Limitations and Assumptions
Attribution is an estimate. Compare at least two models - first-touch, last-touch, multi-touch, or blended - and flag channels whose rankings change. Report both attributed and blended CAC where possible. Count each customer once, keep that definition consistent across months, explain how you allocate shared costs, and reconcile channel CAC with total sales and marketing expense.
The ratio alone doesn't prove profitability. Check it against payback and retention cohorts. Plan around incremental performance, not averages: calculate incremental CAC by dividing added spending by added customers. Expand only when those added customers meet return and payback targets, and when the market, sales capacity, and runway can support growth. Use this channel view before testing how margins change the result.
3. Adjust LTV:CAC for Profit Margins
After comparing channels, adjust LTV:CAC for profit margins to see which customers generate cash. Two channels can have the same CAC but different profit-adjusted LTVs because their delivery costs differ.
Business Question and Decision
Measure customer economics based on profit, not just revenue. Use the results to decide whether to scale, change pricing, improve retention, or cut an unprofitable offer.
Required Financial Inputs
Collect ARPA, direct service costs, customer churn, CAC, and any expansion or contraction assumptions. Keep these inputs tied to the same segment and time period. Direct costs can include hosting, payment processing, support labor, implementation, and third-party usage fees.
Gross margin = (revenue − direct service costs) ÷ revenue
Exclude general administration, taxes, interest, and most sales and marketing costs.
Calculation Method
Pair monthly ARPA with monthly churn.
Subscription LTV = (ARPA × gross margin) ÷ customer churn rate
LTV:CAC = LTV ÷ CAC
The example below keeps CAC the same but replaces revenue-only LTV with profit-adjusted LTV.
Hypothetical illustration - not company results.
Assumption or output Revenue-only Profit-adjusted Monthly ARPA $300 $300 Margin applied 100% assumed 80% gross margin Monthly customer churn 2% 2% LTV $15,000 $12,000 CAC $6,000 $6,000 LTV:CAC 2.5x 2.0x
For non-subscription businesses, use contribution-based LTV = average order value × purchase frequency × customer lifespan × contribution margin. Label each LTV by its calculation method so readers can interpret the ratio.
Limitations and Assumptions
High or unstable churn can make lifetime estimates unreliable. Cap unrealistic lifespans and show a range rather than a single estimate.
Next, use this profit-adjusted view to test how quickly CAC pays back in cash.
4. Calculate CAC Payback
Business Question and Decision
Once LTV is margin-adjusted, check how soon acquisition spending comes back in cash. How long does it take to recover CAC in contribution margin? Use payback alongside LTV:CAC to set acquisition budgets.
A customer may generate a strong lifetime return but take a long time to repay acquisition costs. Compare payback with your cash runway before spending more. A shorter recovery period lets you reinvest sooner and reduces financing pressure.
Required Financial Inputs
Gather fully loaded CAC and monthly contribution margin per customer. Use the fully loaded CAC from the definition above.
Calculation Method
CAC payback (months) = CAC ÷ monthly contribution margin per customer
Payback measures how soon customer profit covers acquisition spending. That profit may mean gross profit or contribution margin, depending on which costs you include.
Calculate payback by cohort and acquisition channel when pricing, sales effort, or variable costs materially affect results. Track cumulative contribution against CAC, then add the recovery schedule to your monthly cash forecast.
Limitations and Assumptions
The formula assumes steady monthly contribution and retention. Economic payback isn't the same as cash payback: prepayments bring cash in sooner, while billing terms and collections can delay it.
Churn can prevent you from recovering CAC at all. Uneven margins also require month-by-month tracking rather than a flat monthly estimate. For prepaid contracts, account for future service costs and state whether the calculation uses earned revenue or collected cash.
| Metric | Formula | Best use | Primary risk |
|---|---|---|---|
| LTV:CAC | LTV ÷ CAC | Evaluate expected lifetime return | Optimistic retention, margin, or expansion assumptions inflate LTV |
| CAC payback | CAC ÷ monthly contribution margin per customer | Set growth pace and assess runway pressure | Billing, collections, churn, and uneven margins delay actual recovery |
Use payback to guide the next step: stress-testing the ratio under different assumptions.
5. Test LTV:CAC Across Scenarios
Business Question and Decision
Stress-test your plan before scaling spend. Use cohort retention, channel CAC, margin-adjusted LTV, and payback to check whether growth still works when retention, acquisition costs, or margins change. Build base, downside, and upside cases.
Set company limits first. If your maximum payback is 12 months, a downside result above that limit should trigger a budget review. Use these scenarios to decide whether to scale, pause, or move spend to other channels.
Required Financial Inputs
Keep the segment and reporting window the same across scenarios. Gather recent cohort data by channel: ARPA, monthly churn, gross margin, fully loaded CAC, expansion revenue, and acquisition-channel mix. Include expansion only when retention data supports it.
For transactional businesses, test average order value, purchase frequency, repeat purchases, and contribution margin. Don’t apply subscription churn mechanically to a different business model.
Calculation Method
Change one driver at a time. Then combine realistic shifts into downside, base, and upside cases.
Use the same margin definition throughout:
- Monthly gross profit = ARPA × gross margin
- Modeled LTV = monthly gross profit ÷ monthly churn
- LTV:CAC = LTV ÷ CAC
- Payback = CAC ÷ monthly gross profit
Illustrative forecast - not observed company results. Include expansion only when retention data supports it.
Scenario Assumptions CAC Modeled LTV LTV:CAC Payback Downside $90 ARPA; 70% gross margin; 4% monthly churn; no expansion revenue; 80% paid-channel share $900 $1,575 1.75:1 14.3 months Base $100 ARPA; 80% gross margin; 3% monthly churn; $5 monthly expansion revenue; 60% paid-channel share $750 $2,667 3.56:1 9.4 months Upside $110 ARPA; 85% gross margin; 2% monthly churn; $10 monthly expansion revenue; 40% paid-channel share $600 $4,675 7.79:1 6.4 months
Tie each trigger to an action. Pause incremental campaign spending when downside payback exceeds your cash-flow limit. Review onboarding when churn exceeds the base assumption for two or three consecutive cohorts.
Update the model monthly. Compare assumptions with actual cohort results for churn, ARPA, gross margin, CAC, expansion, and payback, then reforecast the next 6–12 months.
Limitations and Assumptions
Forecasts are not observed results. A modeled 3:1 ratio can still rely on low churn, inflated ARPA, unproven expansion, or missing costs. Check channel-level results so a strong blended forecast doesn’t hide weak paid-acquisition economics.
Standardize these inputs, definitions, and assumptions before you apply the checklist.
Checklist for Consistent CAC and LTV Analysis
Before comparing frameworks, standardize the inputs they share. Run through this checklist before relying on any CAC:LTV result so cohort, channel, margin, payback, and scenario outputs stay comparable.
- Match units and timing. Use the same customer unit throughout. Document how you handle free trials and reactivations, and assign acquisition costs to cohorts based on when customers become paying customers.
- Check costs and margin labels. Include all acquisition costs. State whether LTV uses gross margin or contribution margin.
- Keep useful segments visible. Show cohort, channel, and blended results. Split segments only where their economics differ, and flag small samples as directional only. Reconcile customer counts and revenue, checking for duplicates, canceled accounts still marked active, and refunds or credits.
- Connect payback to cash. Track CAC payback - not just LTV:CAC - and compare it with cash runway, billing terms, and collection timing.
- Keep inputs current. Update retention and margin inputs at least quarterly, or sooner after pricing, product, or channel changes. Keep historical assumptions separate from forward-looking ones.
- Document definitions. Keep a log of formulas, data sources, inclusion rules, reporting dates, and an owner for each assumption.
Keep accounting records and reporting clean to support reliable inputs. Use these data rules when choosing the framework that fits your decision.
Conclusion: Choose the Framework for Your Decision
Start with the decision, not the ratio. When the numbers disagree, use cohorts to track improvement, channels to guide spending, margins to test profitability, payback to protect cash, and scenarios to stress-test assumptions.
Before scaling spend, cross-check the result with a second framework. Check payback before increasing a channel’s budget. Before relying on a growth forecast, test what happens if retention and collections fall short.
A 3:1 ratio isn’t a stand-alone approval signal. Treat it as a benchmark, not a decision rule. Act only when current inputs and available cash support the move.
FAQs
How can I estimate LTV with limited customer history?
Estimate lifetime value (LTV) conservatively, using industry benchmarks, early engagement data, and customer surveys. Factor gross margin into revenue rather than relying on revenue alone, and cap projections at 5–7 years to avoid overstating customer value.
Early LTV estimates can be shaky. Focus first on your customer acquisition cost (CAC) payback period, ideally 12 months or less, to check your unit economics while you collect data for more precise modeling.
How should I calculate LTV when customer churn is near zero?
When churn is near zero, dividing gross profit by the churn rate can inflate LTV to unrealistic levels. At zero churn, the calculation is undefined. Use a capped customer lifespan instead.
Limit LTV projections to a fixed period, such as 5 to 7 years. This keeps estimates conservative and avoids speculative long-term forecasts. Base the calculation on gross margin, not total revenue.
What should I do when the five frameworks give conflicting signals?
Break down your data by acquisition channel, customer type, or cohort rather than relying on averages. Blended averages can hide problems: a profitable channel may mask another that loses money.
If you don’t have enough data to trust LTV projections, focus on CAC payback period. Track actual cash flow and gross margin - not revenue - while you gather more reliable retention data over multiple years.